
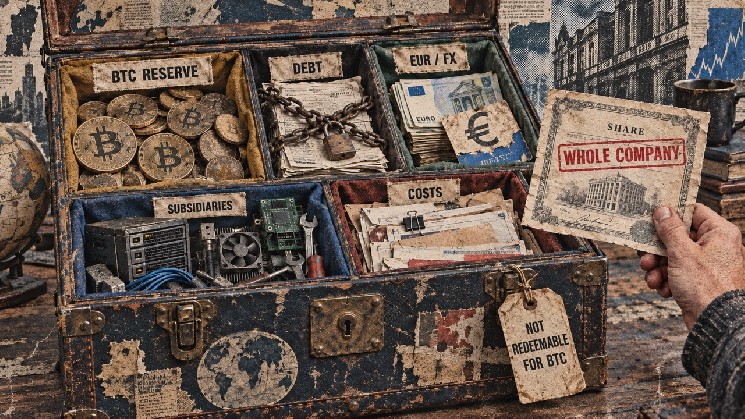
Acquiring shares in a Bitcoin treasury firm entails investing in a business that manages Bitcoin assets, where the leadership determines purchasing strategies and sale timings for the cryptocurrency.
This company needs to cover its financial obligations and may carry debt, thus the value of the shares is influenced by their management decisions and the fluctuating price of Bitcoin.
Capital B, a cryptocurrency treasury firm based in France, exemplifies this relationship clearly. From August 17 to September 7, its Bitcoin reserves rose from 3,145 $BTC to 3,521 $BTC, marking an increase of approximately 12%.
However, the per-share Bitcoin valuation showed minimal change according to the company’s metrics, which factor in potential new shares. This means that although more Bitcoin was acquired, claims to ownership also increased.
This situation highlights the importance of assessing how Bitcoin purchases are financed when evaluating a treasury stock.
Issuing new shares generates funds but dilutes ownership for current shareholders. Borrowing allows maintaining ownership percentages temporarily while creating a repayment obligation. Both strategies can be effective when terms are advantageous, but they still impact the overall investment value.
Capital B trades on Euronext Growth Paris and began implementing its Bitcoin strategy in November 2024. Previously known as The Blockchain Group, it has retained its technology service divisions. Its portfolio includes iORGA, which specializes in web application development, and Trimane, which offers business intelligence and AI consulting services.
Shareholders thus hold a stake not only in the Bitcoin assets but also in the operational costs of its subsidiaries.
Similar to Strategy, Capital B aims to leverage capital investment to acquire Bitcoin. Given its French accounting practices and reliance on euro funding, it operates under a distinct financial framework compared to its American counterparts. This comparison clarifies the value investors gain by entrusting a management team with their investments and the costs associated with that arrangement.
Purchasing Bitcoin can be straightforward
Firms can utilize their business profits to acquire Bitcoin or secure funding from investors and lenders. Each approach creates a different form of ownership claim for the financiers.
Utilizing excess cash from operations does not directly result in additional shares or debt, although this capital could have been used otherwise. Issuing shares generates new funds and results in a broader distribution of ownership. On the other hand, borrowing creates a mandatory repayment commitment, regardless of investment success.
Issuing more shares is not inherently detrimental to existing shareholders. The crucial factor is the issue price, which dictates how much additional purchasing power each new share contributes to the company.
Consider a hypothetical scenario where a business holds 100 $BTC and has 100 shares, with Bitcoin valued at €100,000. If the business issues ten more shares and uses all raised funds to purchase additional Bitcoin, this example simplifies away fees, taxes, operating costs, and loans.
In both situations, each share represents one $BTC. The figures and quantities provided here are hypothetical and do not pertain to Capital B securities.
In the first scenario, existing shareholders have a reduced percentage in a company enriched with additional Bitcoin, leading to a higher amount per share. In contrast, the second scenario fails to maintain the original ratio due to insufficient coin purchases with the new cash.
The success of the first transaction hinges on investors agreeing to pay more for new shares than the current value of an existing one. They might accept the higher price, anticipating profitable future financings by management.
This positive outlook can sustain the process, but if buyers cease to pay the premium, issuing shares will result in acquiring less Bitcoin for each additional share released.
Capital B also raises funds through packages that include regular shares and warrants. Warrants allow holders the option to purchase future shares at predetermined strike prices. Under Capital B’s financing details from August 28, for every share acquired, four warrants are made available, differing in exercise prices and valid for five years.
Investors initially pay for this package and might pay again to exercise their warrants later. This second payment could finance additional Bitcoin acquisitions, but it’s not cash already available in the company’s account. If exercising the warrant is unattractive, the holder may never supply that extra funding.
When warrants are exercised, it both injects cash into the company and creates new shares. Any evaluation of their impact on current owners must encompass both elements, utilizing the exercise price to determine the amount the company would receive.
A convertible debt option is another method for financing Bitcoin purchases. Lenders are granted repayment rights along with a contractual pathway to shares, and the company is obligated to service this debt until conversion occurs.
Capital B has employed Bitcoin-linked convertible financing as outlined in its annual results presentation, alongside its various funding strategies.
Bitcoin-linked financial obligations function differently than fixed-euro loans. If repayment is tied to Bitcoin values, a more valuable reserve could come with a heftier euro obligation. The conversion and repayment conditions dictate this interplay.
Zero-coupon financing avoids the need for periodic interest payments, while lenders may receive compensation through alternative terms, including conversion rights.
Strategy’s U.S. operations utilize common equity, convertible debt, and preferred stock. Preferred shares generally take precedence over common shares for specific claims and may include dividend commitments depending on their terms.
In its July results, the company also indicated Bitcoin sales as a means to partially fund its preferred dividends. Thus, treasury firms can vary significantly in their approach to using Bitcoin and their financing methods.
More coins means more shares
The most noticeable figure in a treasury update is typically the Bitcoin balance. To accurately understand the position of an existing shareholder, that figure must be considered alongside the total share count.
Capital B’s September 7 filing offers the necessary comparison. Its diluted share count includes current shares plus some that could be issued, allowing the firm to project how much Bitcoin each share represents. Satoshis are the tiniest unit of Bitcoin, with 100 million existing in a single $BTC.
All share metrics are based on the pre-consolidation data in the September 7 filing. The reserve does not include specifically designated operational Bitcoin, with the diluted count being defined by the company.
Both the Bitcoin reserve and diluted share count grew by approximately 12%, leaving the ratio effectively unchanged. This ratio compares holdings to a specified number of shares. Shareholders typically lack the right to trade each share for equivalent Bitcoin, and this calculation does not account for the company’s debts.
An administrative event the following day could complicate the comparison with these figures. Capital B’s ten-for-one reverse stock split took effect on September 8, converting ten old shares into one new share. This consolidation lowers the total share count while mechanically boosting the amount attributable to each resulting share without augmenting the company’s assets.
Under this structure, 736.6 satoshis per old share translates mechanically to 7,366 satoshis per new share, adjusting the historical figure into the new unit format. Charts must maintain a consistent share basis to avoid showcasing inflated performance generated purely by consolidation.
The company’s “$BTC Yield” quantifies the percentage change in Bitcoin per diluted share over a given period. Despite its naming, it does not yield any cash dividends to shareholders and reflects a different calculation from their return on investment, as Capital B clarifies in its disclosures.
Shareholders’ actual returns hinge on the prices at which they transact, while corporate obligations modify their claims on assets.
While “fully diluted” might imply inclusion of all potential future shares, company-specific performance metrics can rely on a defined set of assumptions. Capital B’s count encompasses issued shares, assumed shares from convertible bonds, employee incentives, and an additional reserve for potential shares.
To effectively assess outstanding warrants, a distinct exercise scenario must be established, addressing the potential proceeds mentioned earlier. The volume of Bitcoin that these proceeds could procure depends on its price when cash availability occurs.
Conversion adds shares into the equation, but it does not guarantee conversion will happen. If lenders choose to retain repayment claims, common shareholders must account for those claims. Adjusting for debt and presuming the same debt converts simultaneously could also lead to double-counting the liability.
Gross Bitcoin per share figures illustrate the reserve in relation to share count. Net asset value subtracts liabilities from assets, and the market can assign share prices above or below this result.
Accurate comparison of these metrics necessitates consistent assumptions about debt conversion and the capital any new shares would infuse.
What investing in a French firm entails
The European context shapes this model in several ways beyond the trading platform for shares, beginning with currency considerations.
Capital B raises funds and reports most of its metrics in euros. Bitcoin does not represent a dollar claim, despite the prevalence of financial reporting in dollars. The euro price for acquiring it integrates both the widely reported price and the euro-dollar exchange rate.
Assuming Bitcoin holds steady at $100,000. At a rate of $1.25 to the euro, it equals €80,000. Conversely, if the rate is $1 to the euro, it translates to €100,000. These scenarios hypothesize varying exchange rates, illustrating why a stable dollar price for Bitcoin does not ensure a consistent euro value on the balance sheet.
Euro-denominated operating expenses and financing obligations tied to Bitcoin present unique exposures for the firm.
The second distinction lies in the market mechanism for capital acquisition. Euronext Growth serves as a trading platform for smaller firms with regulatory requirements that differ from the mainstream Euronext markets.
As a company in the French corporate framework, Capital B is governed by the associated laws and regulations concerning its securities.
These regulations dictate the conditions under which management can issue shares and the information that must be disclosed to investors. Subscription rights may grant existing shareholders the opportunity to acquire new shares prior to outside investors, enabling them to retain their ownership stake.
Whether these rights apply or are waived varies depending on the transaction. The price point at which Capital B can raise funds also hinges on the demand from investors for its securities.
Accounting practices form the third difference, shaped by the firm and its geographic location.
Capital B’s 2025 consolidated financials adhere to French accounting standards. As part of its stated Bitcoin policy, unrealized gains are reflected through balance-sheet accounts, while unrealized losses may necessitate provisions that impact earnings.
This gap means fluctuations in Bitcoin value can influence reported financial outcomes differently, even if no sales occur.
U.S. regulations for qualifying cryptocurrency require fair-value assessments with market fluctuations reflected in net income, leading to varied earnings results according to FASB standards.
Other European firms might operate under IFRS, where the crypto accounting framework is influenced by the intended use of the assets. Therefore, it is vital to evaluate applicable accounting guidelines on a case-by-case basis among companies.
Company-specific observations based on the referenced disclosures. Neither column reflects every treasury firm in its region; instruments and practices are likely to evolve.
Diverse accounting protocols can complicate the comparison of reported profits among two businesses, even when their assets experience parallel market changes. Valuation entries capture fluctuations in asset value, while the cash available for meeting expenses relies on the firm’s income, expenditure, and financing activities.
Capital B’s 2025 financial summary contextualizes this distinction. It reported a net loss of €62.2 million, mainly due to a €53.9 million impairment on Bitcoin, in conjunction with a positive adjusted EBITDA of approximately €1.2 million from its established operations. The group also reported a negative adjusted EBITDA while detailing around €4.1 million in costs relating to its treasury business.
These figures represent different facets of the business and provide insight into operating efficacy, while cash available for Bitcoin purchases hinges on actual receipts and outgoing payments.
Custodial services, personnel, and corporate financing necessitate resources regardless of management’s intention to retain reserves. Operating subsidiaries can assist in funding these expenses without eliminating them entirely.
Lastly, European investors already have other avenues for corporate treasury exposure. WisdomTree’s Bitcoin product documentation outlines a physically backed exchange-traded debt security. Its structure differentiates it from both direct Bitcoin ownership and shares in Capital B, yet demonstrates that engaging with a treasury company is not the sole method for obtaining the asset in the European market.
Investors must also differentiate between the company’s intrinsic value and its share price. Paying a significant premium for effective management entails an investment today for anticipated future success. Conversely, discounts may compensate purchasers for ongoing corporate expenses or uncertainties regarding new capital access.
Both price points need to be evaluated against the underlying obligations and potential future outcomes.
Favorable capital raises can amplify Bitcoin exposure per share, offering shareholders advantages that direct investments may not afford. However, this benefit must align with corporate expenses and associated financing risks.
For those opting for a passive investment strategy, a restricted mandate may be preferable to circumvent managerial complexities.
Ultimately, Capital B’s attractiveness hinges on the ability of management to secure funds under terms that enhance shareholder value once obligations and costs are accounted for. Its growing Bitcoin reserve plays a crucial role in this assessment.
The shareholder count reveals the extent of diluted ownership, while the financing agreements clarify obligations. Investing in the stock implies a trust in management’s capability to harmoniously align these components at a reasonable cost.