
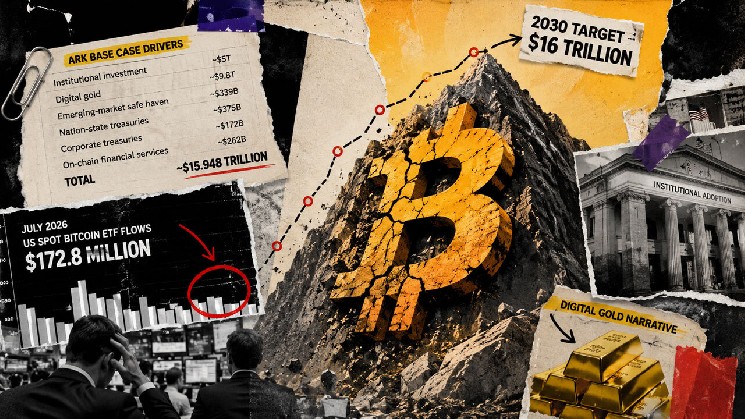
For Bitcoin’s market capitalization to align with ARK Invest’s projected base case of around $16 trillion by 2030, it requires an annual growth rate of approximately 78.6% from its current levels. This optimistic outlook heavily relies on the adoption of Bitcoin as digital gold and increased institutional investment.
According to CryptoSlate, Bitcoin’s market cap is currently close to $1,263,920,244,537. To reach the $16 trillion mark by December 31, 2030, it would necessitate a 12.659-fold increase over just a little more than four years.
However, data from July 2026 indicates a lackluster demand in the prominent U.S. institutional market for Bitcoin ETFs. The latest figures from Farside show a mere $172.8 million in net inflows for U.S. spot Bitcoin exchange-traded funds. While ARK’s forecast extends beyond just one month and one investment channel, the current lower market valuation makes the upward journey more challenging.
The model hinges on two key investments
Understanding Bitcoin’s Market Cap: Variations in Growth Rates
ARK’s Big Ideas 2026 report posits that Bitcoin could see an annual compound growth of around 63% in the five years leading up to 2030, increasing from nearly $2 trillion to about $16 trillion.
The three distinct growth rates are crucial, as each is based on a different starting point or timeline.
ARK’s stated 63% growth rate derives from its own conceptual baseline. If we consider the endpoints as precisely $2 trillion and $16 trillion over five years, this yields an annual growth rate of 51.6%. Conversely, a 63% rate suggesting an endpoint of $16 trillion would imply a starting point near $1.39 trillion—a figure described in ARK’s rounded projections, making direct reproduction of the underlying calculations difficult.
The 78.6% figure reflects a later and lower starting point, calculated from CryptoSlate’s snapshot on August 15, 2026, to the end of 2030, distinguishing it from ARK’s cited rate.
In ARK’s additive framework, six demand factors collectively could yield a modeled market cap impact of approximately $15.948 trillion:
Institutional engagement and the digital-gold narrative contribute a staggering $14.8 trillion, making up 92.8% of the foundational scenario. Thus, the success or failure of the model largely hinges on Bitcoin securing a more significant role in global investment portfolios and fulfilling the monetary function currently attributed to gold. The other four factors collectively account for 7.2% of the model.
July reveals issues in the U.S. ETF market
On July 22, Farside reported daily totals of $172.8 million, while XBTO also noted $172.4 million, characterizing the month of July as the weakest positive period so far in 2026. The discrepancy of $400,000 between the two figures suggests that approximately $173 million represents a more accurate narrative figure.
By annualizing this data, we arrive at a figure of $2.07 billion, derived from multiplying $172.8 million by 12. However, because ETF flows can fluctuate significantly month-to-month, this figure is better viewed as a point of comparison than a projection.
It’s also important to note that ETF net flows and market capitalization are indicative of different market dynamics. ETF data reflects creation and redemption processes, while Bitcoin’s market cap is determined by multiplying the most recent trading price by the circulating supply. Marginal transactions can adjust prices across the entirety of that supply, leading to movements in market value that may not directly reflect the dollars flowing into an ETF.
ARK’s valuation strategy also constructs terminal values based on adoption rates, market accessibility, and anticipated Bitcoin supply. Its evaluation of the institutional segment reflects a modeled value of $5 trillion, derived from a 2.5% penetration within a global portfolio. This does not specifically equate to $5 trillion in ETF subscriptions.
Nonetheless, recent institutional indicators suggest a lack of momentum. BlackRock’s IBIT quarterly report highlighted $4.286 billion in new contributions against $7.236 billion in redemptions, contributing to a net asset decrease of $2.951 billion from capital-share activities. Notably, these transactions can occur in kind, making this data distinct from actual cash flows. IBIT’s shares outstanding increased by a mere 0.4105% from June 30 to July 31.
Market responses to price changes are also unpredictable. ARK estimated that in 2025, U.S. spot ETFs and asset treasuries absorbed 1.2 times the newly mined supply alongside dormant Bitcoin, yet the cryptocurrency’s price fell by 6.2% that same year.
Together, these factors signal July as a cautionary indicator concerning one key pathway to ARK’s institutional ambitions. However, they don’t account for pension allocations, direct custody options, or the complete global market scope considered in ARK’s denominator.
The most significant assumptions have the least support
The current size and observable traction of institutional investments and Bitcoin’s digital-gold status present the greatest risks to this outlook.
In order for the institutional narrative to gain traction, Bitcoin needs to represent 2.5% of ARK’s estimated $200 trillion global portfolio, excluding gold. The U.S. ETF channel is currently the main source for visible daily data, with July revealing negligible net demand. A broader evaluation requires multiple periods of ETF data, direct institutional holdings, treasury allocations, and other custody forms.
Digital gold is estimated to weigh in at around $9.8 trillion; however, this figure is subject to interpretation. As of the end of 2025, the World Gold Council valued above-ground gold at roughly $31 trillion, of which over $15 trillion is deemed investable or financial gold. ARK employs a different input figure of $24.4 trillion regarding the gold market. These variations create discrepancies, positioning ARK’s assessment between the Council’s total-gold and investable-gold measures.
Ultimately, for this base case to hold, there must be clear evidence that Bitcoin is garnering the monetary demand typically associated with gold, rather than merely reaping benefits from a rising gold valuation. ARK has expanded its digital-gold market assumptions following a significant 64.5% increase in gold’s market value throughout 2025.
In contrast, ARK’s assumption regarding emerging markets has moved in the opposite direction. It revised the base-case penetration from 2.5% down to 0.5%, marking an 80% reduction as stablecoins gained traction in developing regions. The International Monetary Fund reported a surge in gross cross-border flows of USDT and USDC, from $12 billion in early 2020 to $316 billion by early 2025, much of which was directed toward emerging markets. This trend highlights the competitive pressures prompting ARK’s substantial adjustment.
Government-backed adoption remains a smaller, policy-driven element. The U.S. Strategic Bitcoin Reserve was initiated in March 2025, funded by forfeited Bitcoin, with a mandate for officials to devise budget-neutral acquisition strategies without requiring funded open-market purchases.
Another legislative proposal aiming to mandate annual purchases of 200,000 $BTC is still under consideration but has not yet been enacted, leaving the current U.S. policy focused on retention rather than active purchasing.
Corporate holdings can fluctuate as well. In a July 6 filing, a company reported selling 3,588 $BTC for $216 million between June 29 and July 5 to fund preferred-stock dividends and strengthen dollar reserves. While this single sale doesn’t reflect the entirety of corporate investments, it illustrates that financial needs can drive treasury holders to sell.
A definable scorecard through 2030
ARK offers a conclusion within its scenario framework. A consistent growth trajectory from the August 15 snapshot allows analysts to set key monitoring benchmarks:
Bitcoin’s trajectory could exceed or fall short of any given target. If two consecutive year-end targets are missed, alongside stagnant or declining evidence regarding institutional investment and Bitcoin’s digital-gold role, the base case could become significantly less credible, given that the required growth rate for the subsequent years would increase.
The 2030 deadline poses a strict examination. According to ARK’s framework, the base case collapses if institutional adoption doesn’t approach 2.5%, if evidence fails to align with a digital-gold component of about $9.8 trillion, and if the six modeled factors don’t support a Bitcoin market cap near $16 trillion.
Monitoring should incorporate a rolling 12-month ETF window, alongside disclosed direct holdings and treasury positions. For digital-gold tracking, we should assess whether Bitcoin’s monetary role and overall market cap align with ARK’s projections. The landscape of stablecoin usage, sovereign acquisition policies, corporate net purchases, and the growth of Bitcoin-related financial services will reveal whether these smaller sectors provide crucial support or exacerbate existing gaps.
With July’s net ETF inflow of about $173 million, the onus is now on institutional pathways to prove their viability. Achieving the $16 trillion scenario relies on visible acceleration in both institutional action and the digital gold narrative, alongside Bitcoin’s market cap maintaining an annual growth rate of 78.6% from the baseline established on August 15.